Credit Card Payoff Calculator — Minimum vs Bigger Payment
See the real interest and time you save by paying more than the minimum on one credit card · free, no signup
Credit Card Payoff Calculator
Enter your card's current balance, its APR and a monthly payment amount. This tool runs real amortization math month by month — applying interest to the remaining balance, then subtracting your payment — to show exactly how many months it will take to pay off and exactly how much total interest you'll pay.
Then enter a second, bigger monthly payment to see the real side-by-side comparison: how many months sooner you'd be debt-free, and exactly how many dollars of interest you'd avoid by paying more than the minimum. This is deliberately focused on one card and the minimum-vs-bigger-payment decision, not a multi-card snowball or avalanche plan — for comparing payoff order across several debts at once, see the separate Debt Payoff Calculator (Snowball vs Avalanche).
Key features
Real month-by-month amortization
Interest is applied to the true remaining balance each month, not a flat estimate.
Total interest and payoff time
See exactly how many months and how many real dollars of interest a payment plan costs.
Minimum vs bigger payment comparison
Enter two payment amounts and see the real savings side by side.
Single-card focus
Built specifically for one card's minimum-vs-more decision, distinct from multi-debt payoff planning.
How to use it
- Enter your card balance and APR.
- Enter your current (or minimum) monthly payment.
- Enter a bigger monthly payment to compare.
- See real total interest, payoff time, and exactly what paying more saves you.
Worked example
Example
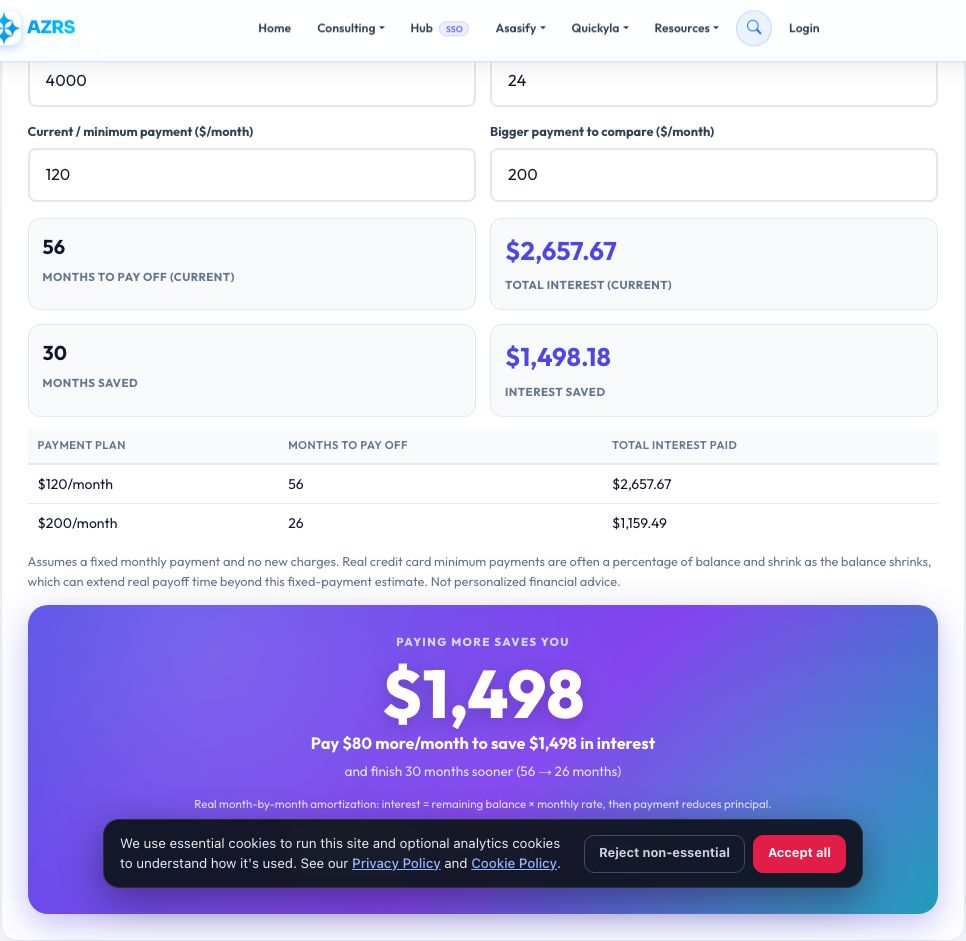
$4,000 balance, 24% APR, $120/month minimum → about 56 months and $2,658 total interest. Bumping to $200/month → about 26 months and $1,159 total interest — 30 months sooner and about $1,498 less interest.
Who uses this tool
Anyone carrying a credit card balance
See the real cost of only paying the minimum, in actual dollars and months.
People deciding how much extra to pay
Compare a couple of payment amounts before committing to a budget.
Anyone consolidating or refinancing debt
See a clear before/after baseline for a single card's real payoff cost.
Tips for the best results
- Even a modest increase over the minimum payment often cuts total interest dramatically, because credit card APRs compound on a shrinking balance more slowly when paid down faster.
- Check your card's real minimum payment formula — some cards use a percentage of balance, which shrinks as the balance shrinks, extending payoff time far beyond a fixed dollar minimum.
- Stop new charges on a card you're actively paying off, or the real payoff time shown here will be optimistic.
Common mistakes to avoid
- Assuming the minimum payment stays fixed in dollars — many real minimums are a percentage of balance and shrink over time, meaningfully extending real payoff time beyond a fixed-payment estimate.
- Ignoring the APR compounding monthly, not just yearly, which is why paying only the minimum can take years longer than it feels like it should.
- Comparing this single-card tool's output to a multi-card debt plan — for several debts at once, the separate Debt Payoff Calculator (Snowball vs Avalanche) is the right tool.
Why use AZRS QuickFix?
It is 100% free, needs no signup and has no watermark or usage limits. The tool runs in your browser, so what you type stays on your device, and it works on phones, tablets and desktops. New tools are added every week — bookmark this page or browse the full QuickFix toolbox.
Frequently asked questions
How is this different from the Debt Payoff Calculator?
That tool compares snowball vs avalanche payoff order across multiple debts at once; this tool focuses on one card and the specific minimum-payment-vs-bigger-payment decision, with a real side-by-side interest and time comparison.
Is the interest calculation exact?
It runs real month-by-month amortization (interest applied to the remaining balance, then payment subtracted), which matches how credit card interest actually compounds, assuming a fixed payment and no new charges.
What if my payment doesn't cover the monthly interest?
The calculator will flag this — if your payment is less than the interest accruing each month, the balance never goes down, and it's shown plainly rather than returning a misleading payoff date.
Does this include a real minimum-payment formula?
You enter your own payment amount, since real minimum-payment formulas vary by issuer; if your card's minimum is a percentage of balance, using a fixed dollar estimate here will understate real payoff time somewhat.
Is this financial advice?
No, it's transparent amortization math on your own numbers, not personalized financial advice.
Is my data stored?
No, everything is calculated locally in your browser.